

M2P Fintech
Fintech is evolving every day. That's why you need our newsletter! Get the latest fintech news, views, insights, directly to your inbox every fortnight for FREE!
Reserve Bank of India (RBI) released the latest Digital Lending (DL) guidelines on September 2nd, 2022. This notification confirmed the implementation of the recommendations specified in Annex-1 of the RBI press release**, published a few weeks ago.
Before deep diving into these guidelines, let us understand the RBI’s role as a regulator in the Indian economy.
A book by Dr. B. R. Ambedkar sparked the idea of setting up a central banking institution for India. Subsequently, on April 1, 1935, RBI started its operations based on the RBI act of 1934. The act provides the statutory basis for the functioning of the bank. Yet, RBI remained a private institution till it was nationalized in 1949. Since then, RBI has been regulating, moderating, and monitoring the financial aspects of the country’s fiscal and economic position.
The primary functions of RBI include the following.
Other than these, RBI’s role also includes stabilizing India’s financial reserves. They work with players such as financial institutions, regulatory bodies, fintechs, and government agencies to ensure the smooth flow of financial services. To summarize, all private and public banks are monitored by RBI to build trust and safety among their users.
In the last eight years, fintechs, online/mobile banking, and other technological advancements have modernized the financial ecosystem worldwide. Digital transformation in financial services is on a rapid growth spurt. And in recent years, digital lending has been a prominent topic in the industry with its share of pros and cons.
According to RBI reports, Digital Lending (DL) is “A remote and automated lending process, majorly using seamless digital technologies in customer acquisition, credit assessment, loan approval, disbursement, recovery, and associated customer service.”
Now that the definition clearly states what constitutes digital lending, let's see who the players are and their roles in the DL realm.
The key players listed above contribute to the remarkable growth of the industry.
The pandemic era witnessed phenomenal growth in online transactions. There was a significant rise in digital lending platforms and applications. As a result, applying for and borrowing money from a digital lender got simplified, thus giving rise to thousands of Digital Lending Applications (DLAs).
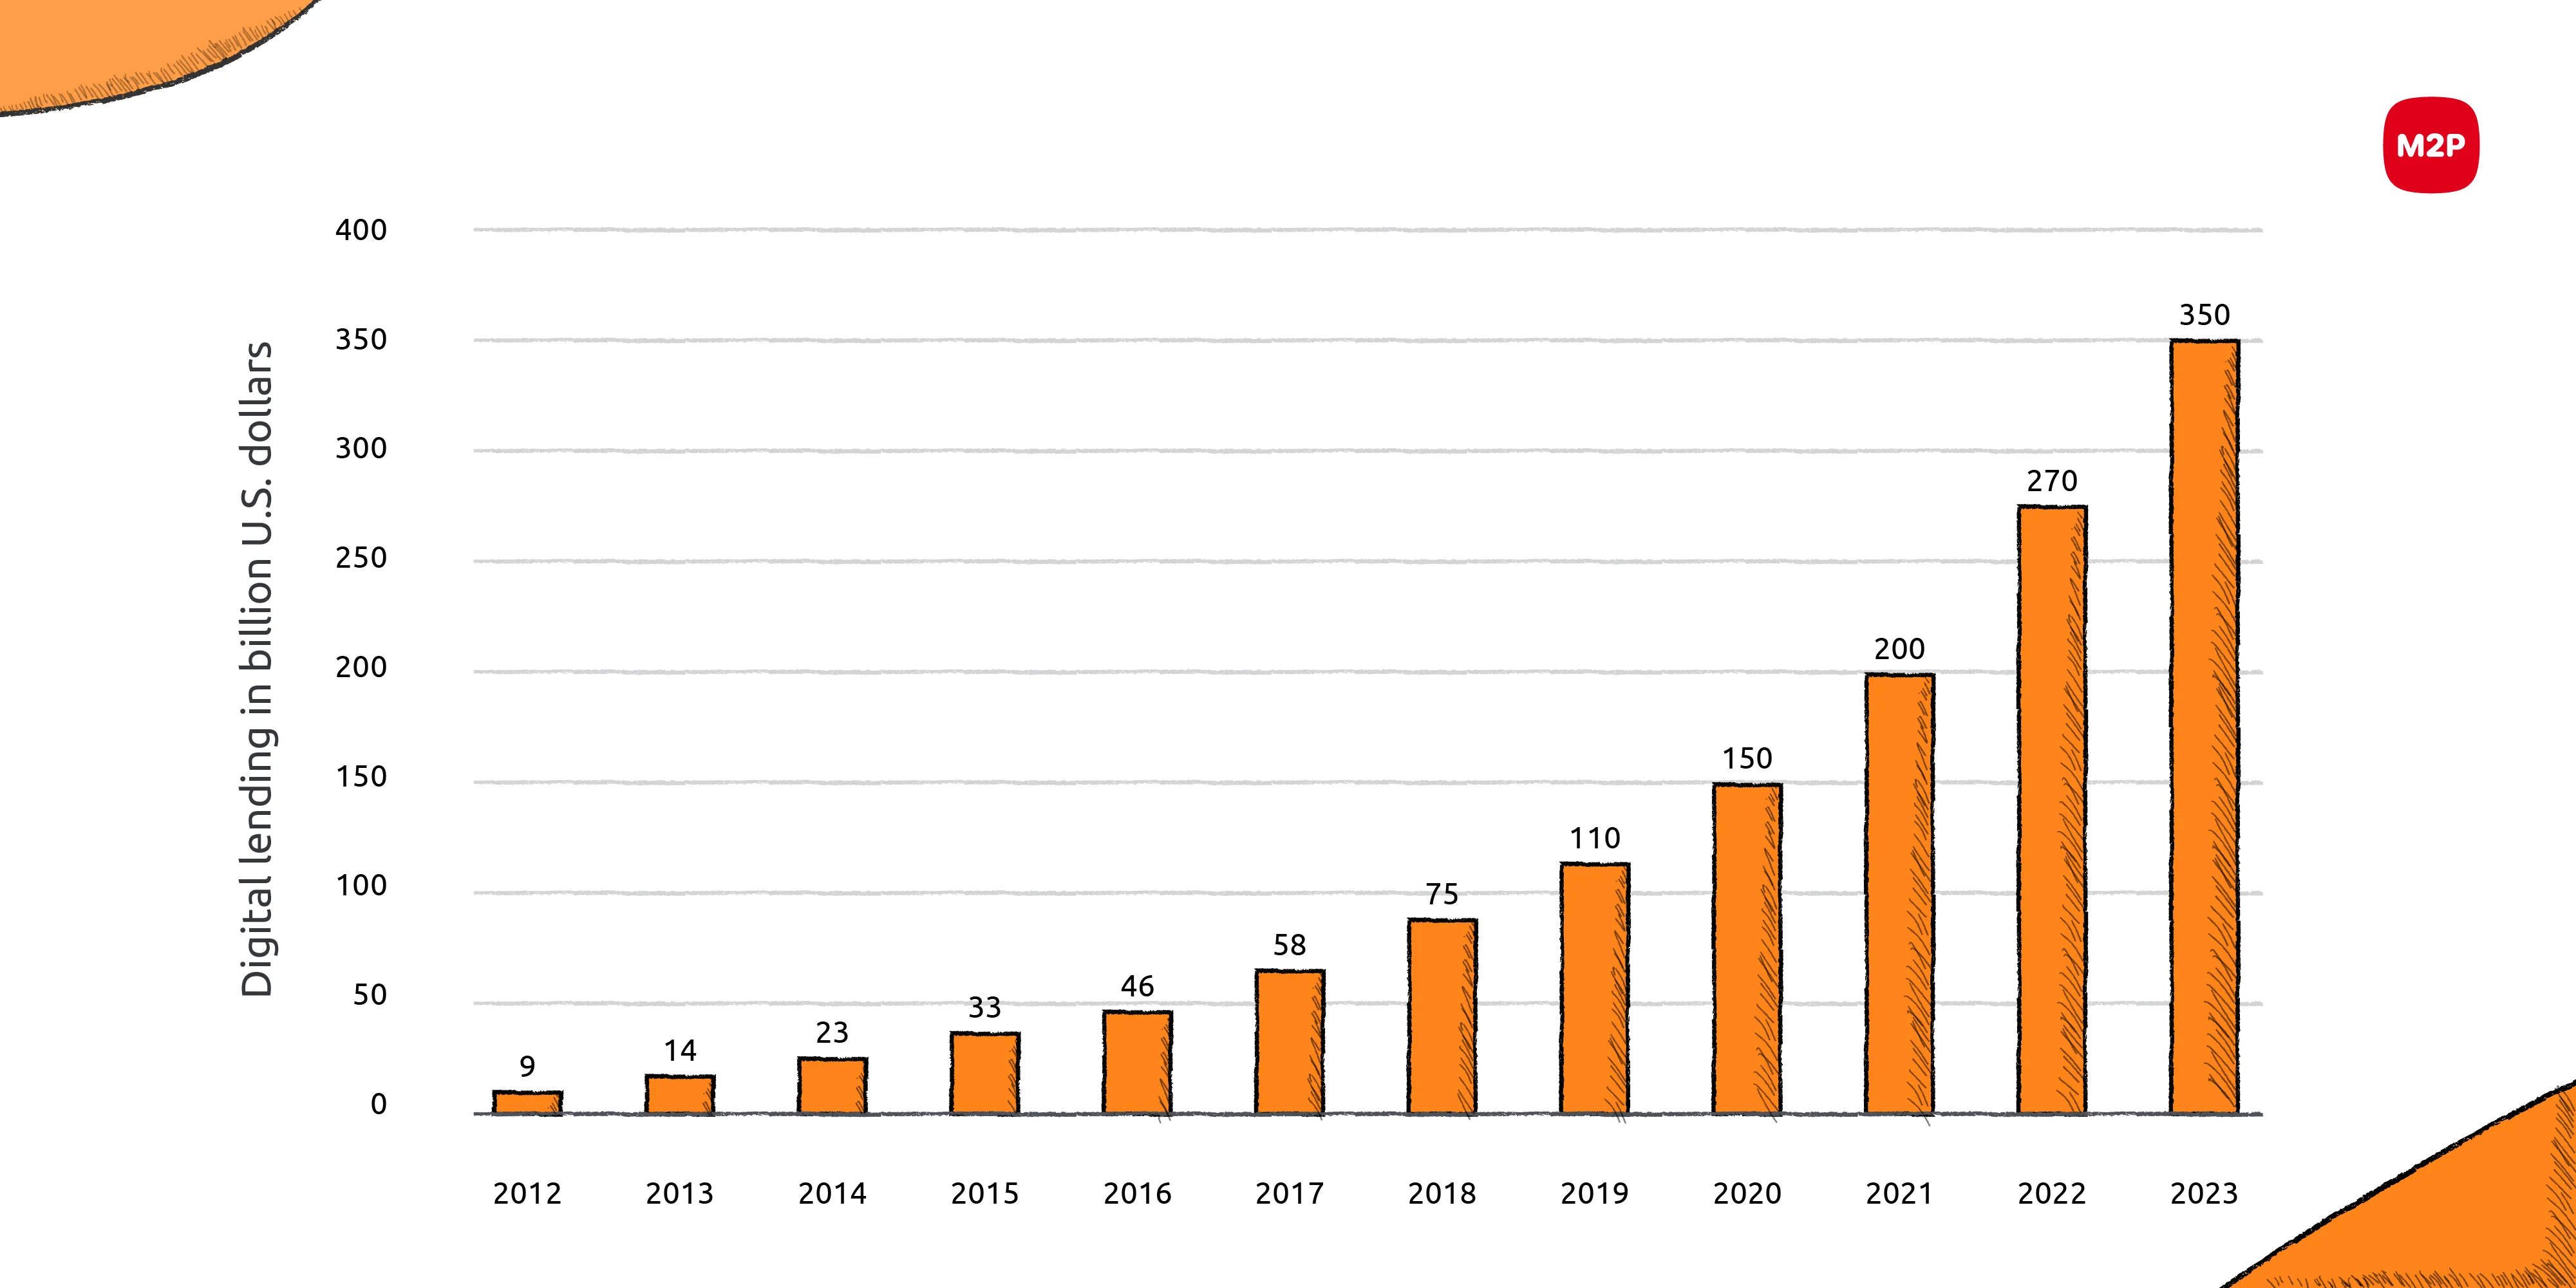
Digital Lending (DL) recorded one of the highest growth in India, from $9bn in 2012 to around $110 bn in 2019. By 2023, the value of the digital lending industry is expected to reach $350 Bn dollars.
When we talk about DL, First Loss Default Guarantee (FLDG) is the term we hear quite often. It is one of the many triggers of RBI's DL regulation.
Let's get a quick glimpse into what FLDG is.
We'll start with a simple example. In trading communities, family businesses are carried on from one generation to the next. When entrepreneurs emerge in these situations, loans are given to them based on the family's credibility. The reason is that if they do not make a payment, the lender can recover it from the borrower’s family.
Likewise, in the case of First Loss Default Guarantee (FLDG), whenever a borrower defaults, a third party (fintech, in this case) comes in to compensate the lender. This mechanism is FLDG.
Here's how FLDG works.
Few NBFCs were renting out their licenses through FLDG. This enabled LSPs to build a proxy portfolio which some industry experts claim to be a risk to the lending system.
While FLDG contributed to the industry's increasing volume, several unregulated entities came into the picture. They exploited customer data and resorted to illicit collection activities. Many borrowers faced serious trouble as they were unaware of the real nature of these entities. An alarming rise in customer complaints resulting from the actions of the unregulated entities placed digital lending on RBI’s radar.
To address and streamline the same, RBI set up a Working Group (WG) to understand the risks and set up necessary controls in the DL industry.
On January 13, 2021, RBI set up a WG consisting of thirty-six stakeholders. The purpose was to study the DL industry and its activities in detail and to implement the right regulatory approach.
The WG surveyed and studied the industry and presented a report (containing two annexures) to RBI on November 18, 2021. The report’s findings were based on the following pillars.
After considering the recommendations, RBI officially announced the implementation of the DL guidelines on September 2, 2022.
The following recommendations were accepted by RBI for immediate implementation.
The following recommendations were accepted in principle but require further examination.
The latest guidelines emphasize the importance of protecting borrowers by curbing the misuse of digital lending apps. The REs are given time until November 30, 2022, to develop systems and processes that are compliant with the ruling.
Undoubtedly, fintech-led digital lending will certainly undergo changes. The larger perspective is to protect the customers and the economy from unscrupulous practices and uphold the trust of the banking system.
Reference**: Annexure 1 of RBI press release
Want to know more about digital lending? Write to us at business@m2pfintech.com.
Subscribe to our newsletter and get the latest fintech news, views, and insights, directly to your inbox.
Follow us on LinkedIn and Twitter for insightful fintech tales curated for curious minds like you.


Fintech is evolving every day. That's why you need our newsletter! Get the latest fintech news, views, insights, directly to your inbox every fortnight for FREE!