

M2P Fintech
Fintech is evolving every day. That's why you need our newsletter! Get the latest fintech news, views, insights, directly to your inbox every fortnight for FREE!
Debit cards remain one of the most deeply anchored layers of the payment ecosystem. Even as Unified Payments Interface (UPI) and credit cards dominate high-frequency retail transactions, the sheer footprint of debit cards remains massive: as of late 2025 / 2026, there are over 1.03 billion outstanding debit cards in force in India. While everyday POS and online transaction volumes have shifted toward UPI, debit cards remain the essential, secure backend plumbing of Indian banking - driving high-volume ATM activity, enabling cardholder authentication, and serving as the primary account-access tool for over a billion users.Highly secure and effortless to use, debit cards let cardholders instantly tap, enter a PIN, or tokenise their credentials for cashless transactions, drawing directly from an existing bank balance with zero interest or debt risk.
This guide covers what debit cards are, the types issuers offer, the regulatory rules issuers must follow, and new for this update - a practical walkthrough of how a bank, NBFC, or fintech actually becomes a debit card issuer in 2026.
Debit cards are payment instruments linked directly to a bank account, issued by banks and NBFCs to individuals and corporate entities. They're used for in-store and online payments, fund transfers, and cash withdrawals. Funds move from the cardholder's account to the recipient's account in real time, at the moment of transaction - there's no credit extended and nothing to repay later.
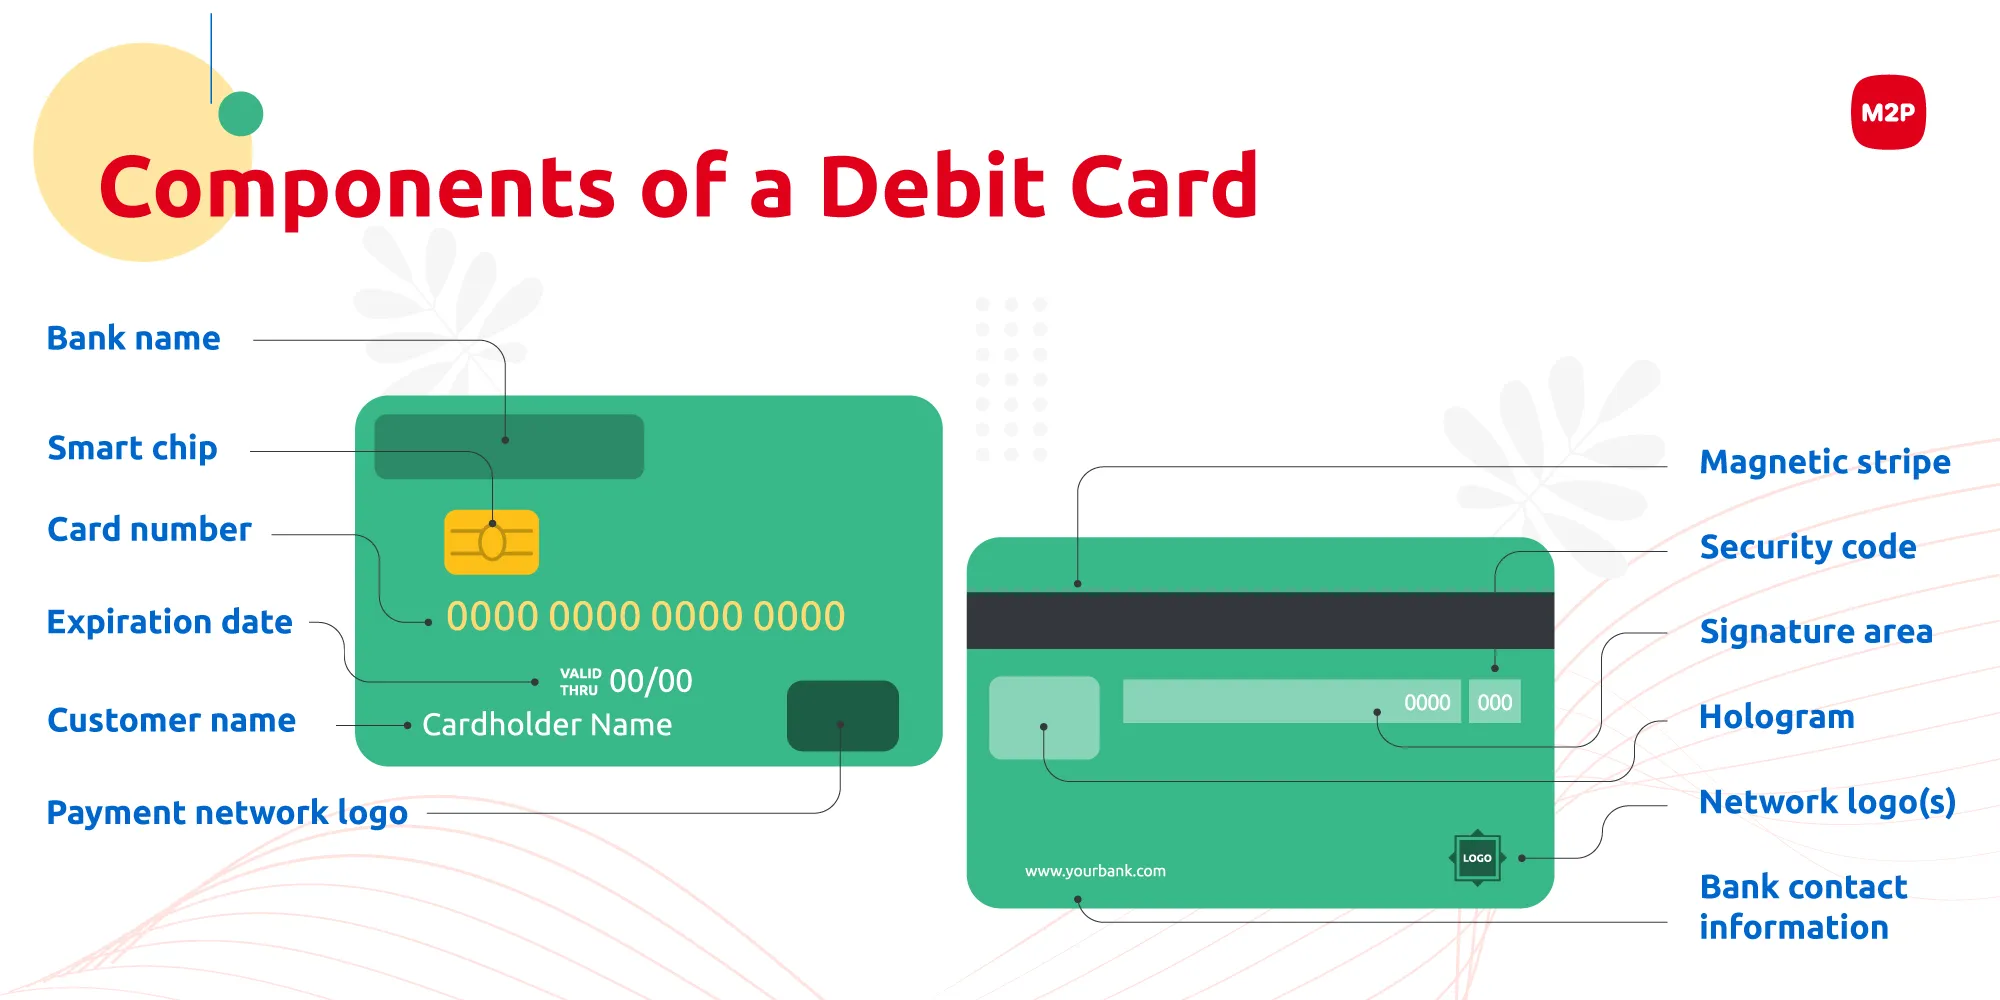
Here are the key components of a debit card.
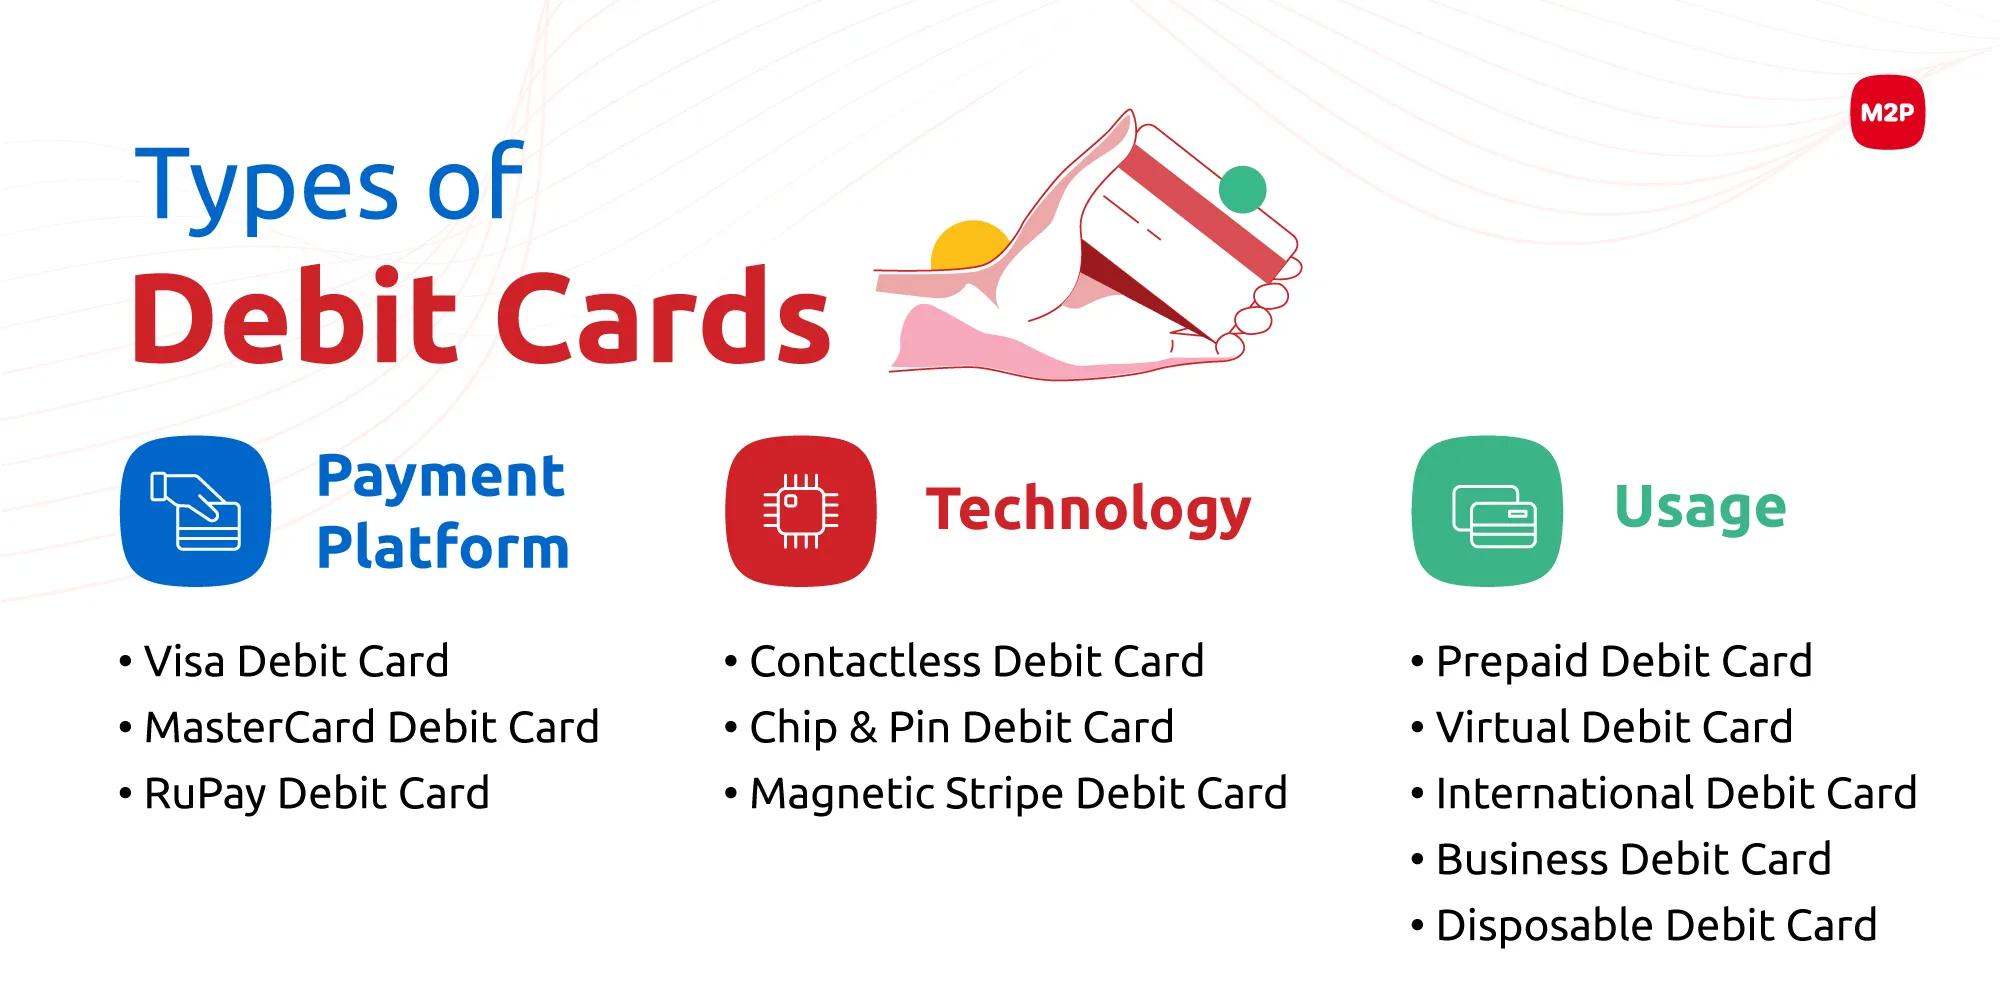
Banks and NBFCs classify debit cards by payment network, technology, and use case.
Becoming an issuer isn't a single license application - it's a stack of decisions, each with its own vendor and compliance layer. Here's how banks, NBFCs, and neobanks typically approach it today.
A Bank Identification Number (BIN) is what ties a card to a network and a settlement bank. Licensed banks apply for and hold their own BIN directly with the network (Visa, Mastercard, RuPay). Non-banks and neobanks that want to issue cards but don't hold a banking license instead enter a BIN sponsorship arrangement - partnering with a sponsor bank that lends its BIN and regulatory standing, while the non-bank runs the customer-facing program. This is the single most important early decision, since it determines who carries ultimate regulatory accountability.
Once sponsorship is in place, the next decision is the technology layer that actually issues, manages, and processes the cards - card creation, PIN management, transaction authorization, limits, controls, and lifecycle management. Legacy CMS platforms are slow to configure and typically take 12+ months to launch a program. Modern API-first CMS platforms, like M2P's, compress that timeline to weeks by handling BIN application support, issuer processing, card printing and fulfillment coordination, mobile wallet tokenization, and scheme contract management under one stack - plus a proprietary card switch and ACS (authentication gateway), which most other providers don't offer natively.
Whichever network the card runs on - RuPay, Visa, or Mastercard - the issuer (or its CMS partner) needs to complete technical certification and testing with that network's directory server and processing systems. This step governs how transactions authorize, settle, and route, and it needs to be repeated for every network the program supports.
RBI mandates apply from day one: customer KYC at onboarding, adherence to the debit card issuance directives below, and ongoing reporting obligations. For BIN-sponsored programs, compliance is a shared responsibility between the sponsor bank and the technology/program partner - but the sponsor bank remains accountable to the regulator regardless of who built the tech.
While the foundational rules from 2022 remain active, the RBI has introduced several critical amendments through its 2024, 2025, and April 2026 Master Directions that modern issuers must follow:
New card issue refers to the technical process behind creating a fresh debit or credit card for a customer, distinct from a reissue or replacement. It typically involves three steps:
A few shifts have become standard practice since this guide was first written:
Legacy infrastructure was built for a slower, less customized era of card issuance. It struggles to support the range of card programs, personalization, and go-to-market speed that today's issuers need. Standing up a card program on legacy rails can take the better part of a year — a lag that shows up directly as lost cost, effort, and competitive ground.
An API-first card issuing platform lets issuers build differentiated debit products without inheriting legacy constraints. Hosted on cloud infrastructure, these platforms scale with the business and adapt as new use cases and regulatory requirements emerge.
With M2P's API-based debit card platform, issuers can go to market with a full debit card program in weeks. That includes BIN sponsorship support, issuer processing, card printing and fulfillment coordination, mobile wallet tokenization, and scheme contract management - backed by a proprietary card switch and ACS, features most other providers don't offer in-house.
Issuers get custom controls, real-time data-driven transaction authorization, and the ability to launch virtual and disposable cards alongside physical ones. The platform covers core issuing, processing, and back-office operations - including reconciliation and chargeback handling - plus support for marketing and customer service. Programs are modular, so issuers can adopt what fits their current stage of readiness.
Want to know more about launching a debit card program? Talk to us today!
Subscribe to our newsletter and get the latest fintech news, views, and insights, directly to your inbox.
Follow us on LinkedIn and Twitter for insightful fintech tales curated for curious minds like you.


Fintech is evolving every day. That's why you need our newsletter! Get the latest fintech news, views, insights, directly to your inbox every fortnight for FREE!